
Diversifying across residential, commercial, and industrial property feels like a complete risk management strategy — and it genuinely helps with market-specific volatility. But it has a real blind spot most investors never think through: even a portfolio spread across every property type still sits entirely within the same country’s legislative, economic, and regulatory environment. A national tax law change, a systemic interest rate move, or a broad economic downturn affects residential, commercial, and industrial assets simultaneously, regardless of how carefully you’ve spread your capital across those categories. Genuine risk reduction requires understanding which risks diversification actually solves, and which ones it structurally cannot.
The Four-Step Risk Management Process
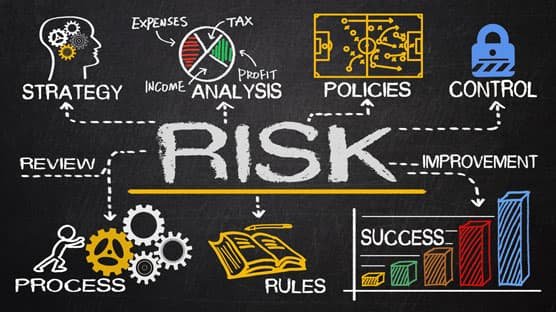
Before looking at specific techniques, it helps to understand the structured process serious investors actually follow, rather than treating risk management as a loose collection of individual tactics.
- Identification — recognizing potential risks across financial, legal, operational, environmental, and market-related categories before they materialize into actual losses
- Assessment — quantifying potential exposure through cash flow analysis, stress testing, legal review, and market assessment, giving a clearer sense of how severe each identified risk genuinely is
- Prioritization — ranking risks by severity and probability together, since not every risk deserves equal attention; high-impact, high-probability risks get addressed first, while lower-priority issues simply get monitored over time
- Mitigation — implementing the actual protective measures — insurance, diversification, legal due diligence, strong lease agreements, preventive maintenance — matched specifically to the risks that ranked highest in the prioritization step
Diversification: What It Actually Protects Against, and What It Doesn’t
This is where the earlier caveat matters most, since diversification genuinely works for some risks and does essentially nothing for others.
- Spreading investment across different property types and geographic locations meaningfully reduces exposure to any single market or asset underperforming — if a residential unit in one city sits vacant, income from a commercial property in a different city can offset that gap
- This kind of diversification genuinely protects against property-specific and localized market risk — a single building’s tenant default, a specific neighborhood’s temporary softness, one micro-market’s oversupply
- What it doesn’t protect against: systemic risk operating at the national level — a regulatory change, an economy-wide downturn, or a broad interest rate shift affects every property type and every city within that same jurisdiction simultaneously
- Genuinely comprehensive diversification, for investors with the capital to pursue it, extends beyond property type and city to include different regulatory jurisdictions entirely — something most individual Indian real estate investors realistically can’t achieve through direct property ownership alone, which is part of why REITs and other pooled structures increasingly factor into serious portfolio construction
Reserve Funds: Sizing Your Liquidity Buffer for Real Stress Scenarios
A cash reserve isn’t just prudent financial habit — it’s a specific, quantifiable risk management tool with a genuine sizing methodology behind it.
- A commonly cited guideline sets aside 6-12 months’ worth of operating expenses per property as a liquidity buffer, though the appropriate figure depends on your specific property’s income stability and your own broader financial cushion
- This reserve exists specifically to cover realistic stress scenarios, not just normal operations — temporary vacancy between tenants, unplanned repairs, delayed rental payments, or a short-term market correction affecting your ability to sell or refinance on your original timeline
- A professional-grade liquidity buffer accounts for these stress scenarios happening simultaneously, not just one at a time, since real financial pressure often arrives from multiple directions during a genuine downturn
- Maintaining this buffer isn’t about concealing poor planning — it’s about preserving your ability to make deliberate decisions rather than being forced into a rushed sale or distressed refinancing when your original assumptions don’t hold
Managing Leverage Deliberately, Not Just Maximizing It
Debt genuinely amplifies real estate returns, as covered in how leverage boosts effective IRR — but that same mechanism cuts both ways, and disciplined leverage management is itself a core risk mitigation technique.
- Keeping loan-to-value ratios conservative, rather than borrowing up to the maximum a lender will approve, leaves genuine breathing room if property values soften or rental income temporarily declines
- Considering fixed-rate loans specifically for the protection they offer against fluctuating interest rates, rather than defaulting purely to whichever rate structure offers the lowest starting payment
- Excessive leverage can push an otherwise sound investment into genuine financial distress during an economic downturn or a rate hike cycle, precisely because a highly leveraged position has far less capacity to absorb reduced income or rising financing costs
- Combining conservative LTV ratios with healthy cash reserves specifically for each leveraged property creates a meaningfully more resilient position than either safeguard alone
Insurance as a Genuine Risk-Transfer Tool
Property insurance functions as a direct mechanism for transferring specific, quantifiable risks away from your own balance sheet entirely.
- Standard property insurance covers risks like fire, natural disasters, theft, and structural damage, protecting the physical asset itself against events that would otherwise represent a total or partial capital loss
- Liability coverage protects against claims arising from accidents occurring on your property, a genuinely distinct risk category from physical damage to the asset itself
- Working with an experienced insurance agent to customize coverage specifically for each property, rather than accepting a generic default policy, ensures the coverage actually matches your property’s genuine risk profile
- Reviewing policy terms carefully to understand exactly what’s covered, and purchasing additional coverage where genuine gaps exist, prevents the unpleasant discovery of an uncovered loss precisely when you need the policy to actually perform
Legal and Regulatory Risk: Where Due Diligence Becomes Risk Management
Thorough upfront verification isn’t separate from risk management — it’s one of the most effective mitigation techniques available, precisely because it prevents entire categories of risk from ever entering your portfolio in the first place.
- Confirming clear title, verifying RERA compliance status, and reviewing zoning and land-use restrictions before acquisition prevents legal disputes that can otherwise consume years and substantial capital to resolve after the fact
- Structuring lease agreements carefully — covering escalation terms, maintenance responsibilities, and exit provisions clearly — reduces the likelihood of costly disputes with tenants down the line
- Staying genuinely informed on policy and regulatory changes, rather than treating your initial due diligence as a one-time event, lets you adapt your strategy proactively rather than discovering a consequential regulatory shift only after it’s already affected your portfolio
- Legal verification and strong documentation function as risk prevention rather than risk mitigation after the fact — the cheapest way to handle a legal or title dispute is ensuring it never becomes possible in the first place
Alternative Structures That Build In Diversification From the Start
For investors specifically concerned about concentration risk in a single, direct property, several structural alternatives build diversification into the investment vehicle itself.
- Real estate crowdfunding platforms let multiple investors pool capital across several projects simultaneously, providing built-in diversification with meaningfully lower capital requirements than acquiring several individual properties directly would demand
- Real Estate Investment Groups (REIGs) offer exposure to a pooled portfolio of properties without the operational burden of direct property management, functioning somewhat like a smaller-scale, less liquid cousin to a REIT
- Both structures shift some genuine due diligence responsibility onto the platform or group itself, which means evaluating the platform’s or group’s own track record and governance becomes an essential additional layer of due diligence before committing capital
- These structures don’t eliminate the systemic risk discussed earlier — a pooled portfolio still sitting entirely within one country’s regulatory environment carries the same national-level exposure as direct ownership — but they do meaningfully reduce property-specific and tenant-specific concentration risk for investors without the capital to build that diversification through direct ownership alone
This is general educational information about real estate risk management, not investment advice. Specific risk factors and appropriate mitigation strategies vary by investor, property, and market conditions, and independent professional guidance is essential before making significant real estate investment decisions.
FAQs
Q1. Does diversifying across residential, commercial, and industrial property fully protect my real estate portfolio from risk?
A: No. This kind of diversification genuinely reduces property-specific and localized market risk, but it doesn’t protect against systemic risk — a national regulatory change or economic downturn affects every property type within the same jurisdiction simultaneously.
Q2. How much cash reserve should I actually keep for a rental property investment?
A: A commonly cited guideline is 6-12 months of operating expenses per property, sized to cover realistic stress scenarios like extended vacancy, unplanned repairs, and delayed rental income occurring together rather than individually.
Q3. Is taking on more leverage always a bad risk management decision?
A: Not inherently — leverage amplifies both returns and risk, so the key is deliberate management through conservative loan-to-value ratios, healthy cash reserves, and considering fixed-rate loans, rather than avoiding leverage entirely or maximizing it without discipline.
Q4. Are real estate crowdfunding platforms a genuinely safer way to diversify than buying property directly?
A: They can reduce property-specific and tenant concentration risk with lower capital requirements, but they shift due diligence responsibility onto the platform itself, making the platform’s own track record and governance an essential additional check before investing.